Key Takeaway
What to check when New York no-fault benefits run out: the payment ledger, additional PIP, health coverage, unpaid bills and a separate injury claim.
This article is part of our ongoing car accidents coverage, with 228 published articles analyzing car accidents issues across New York State. Attorney Jason Tenenbaum brings 24+ years of hands-on experience to this analysis, drawing from his work on more than 1,000 appeals, over 100,000 no-fault cases, and recovery of over $100 million for clients throughout Nassau County, Suffolk County, Queens, Brooklyn, Manhattan, and the Bronx. For personalized legal advice about how these principles apply to your specific situation, contact our Long Island office at (516) 750-0595 for a free consultation.
When no-fault benefits run out, the next step is to confirm what was paid and identify other coverage before treatment bills become a surprise. Exhaustion does not, by itself, end a separate personal-injury claim.
It also does not guarantee that another insurer will pay. The policy, the kind of expense and the reason payments stopped all matter.
New York No-Fault Insurance: The Basics
Basic New York no-fault coverage generally provides up to $50,000 per eligible injured person for combined medical expenses, lost earnings and other necessary expenses.
DFS’s auto-insurance guide explains the limits: wage benefits are generally 80% of lost earnings, capped at $2,000 monthly for up to three years, with statutory offsets.
Free Consultation · No Fee Unless We Win
Does this apply to your situation?
Every case is different. Get a free, confidential case review from an experienced attorney who can tell you exactly where you stand.
Other necessary expenses generally have a $25 daily limit for up to one year. These benefits share the basic limit; they are not separate $50,000 funds.
Coverage is not universal. Motorcycle occupants, for example, are excluded from basic no-fault benefits. The responsible insurer also depends on the injured person’s role and the vehicles involved.
What “No-Fault Exhaustion” Means
Exhaustion means that payments chargeable to an applicable coverage limit have used it up. A denial based on medical necessity, missing verification or a coverage exclusion is a different problem.
Ask for written confirmation of:
- The coverage and limit the insurer says are exhausted.
- The exhaustion date and payment ledger.
- Payments for medical care, wages and other expenses.
- Any additional coverage or remaining benefits.
- The reason each unpaid bill was denied.
Compare the ledger with the bills and explanations of benefits. Do not assume that an unpaid bill proves exhaustion, or that the insurer’s accounting cannot be questioned.
Where to look for additional coverage
Start with the declarations and endorsements for the occupied vehicle and potentially applicable household policies.
DFS’s no-fault FAQ identifies Additional PIP and, if that is unavailable, a claim to standard health insurance as possible next steps.
Optional Basic Economic Loss coverage, or OBEL, is different: Insurance Law § 5102(a)(5) describes an optional $25,000 allocation for specified losses after basic benefits are exhausted.
Ask what was purchased, who qualifies and which expenses it covers. Do not assume OBEL can pay every kind of medical bill.
If the crash happened during work, investigate workers’ compensation and no-fault coordination. Do not treat workers’ compensation as simply another fund to spend after PIP.
Keeping treatment and billing organized
Give your provider the written coverage decision and ask its billing staff what the next payer needs. Confirm network rules, authorization requirements and patient responsibility before relying on a change in coverage.
A provider’s agreement to defer collection is not health insurance. Ask what remains payable if a lawsuit produces no recovery, and have counsel review any proposed settlement-based payment agreement.
DFS’s opinion on fees after exhaustion explains that exhaustion does not itself free covered accident-related services from applicable no-fault fee-schedule limits.
Keep an itemized record of disputed and unpaid amounts. The medical-expenses guide sets out a practical tracking checklist.
Does exhaustion end the claim against another driver?
No. But coverage exhaustion and the right to recover damages answer different questions.
Insurance Law § 5104 restricts recovery of basic economic loss and generally requires serious injury for non-economic damages in covered-person auto cases.
Economic loss beyond the statutory basic-loss limits requires separate analysis. Spending $50,000 does not itself establish negligence, serious injury or the amount recoverable.
The applicable version of CPLR 1411, including its motor-vehicle fault restriction, can also affect recovery. Counsel must check applicability to the accident and claim.
Two decisions worth reading first
Exhaustion fights are usually won or lost on the carrier’s payment record. Two notes from the firm’s case archive show how that plays out: Easy Care (2016): the payment record behind a contested exhaustion defense, and Mendoza (2015): an IME cut-off that was never rebutted, where the physical-therapy claims failed for want of proof rather than for want of coverage.
What to bring to a coverage review
Bring the policy, claim number, accident date, exhaustion letter, payment ledger, unpaid bills and any health-plan denials. Include wage records and details of work-related travel where relevant.
A lawyer can then distinguish a billing dispute from a coverage dispute and assess the separate car-accident injury claim.
Do not wait for every benefits dispute to be resolved before checking filing deadlines. This guide provides general information, not a coverage decision or a promise of recovery.
Legal Context
Why This Matters for Your Case
New York law is among the most complex and nuanced in the country, with distinct procedural rules, substantive doctrines, and court systems that differ significantly from other jurisdictions. The Civil Practice Law and Rules (CPLR) governs every stage of civil litigation, from service of process through trial and appeal. The Appellate Division, Appellate Term, and Court of Appeals create a rich and ever-evolving body of case law that practitioners must follow.
Attorney Jason Tenenbaum has practiced across these areas for over 24 years, writing more than 1,000 appellate briefs and publishing over 2,353 legal articles that attorneys and clients rely on for guidance. The analysis in this article reflects real courtroom experience — from motion practice in Civil Court and Supreme Court to oral arguments before the Appellate Division — and a deep understanding of how New York courts actually apply the law in practice.
About This Topic
Car Accident Law in New York
Car accidents in New York involve both no-fault insurance claims for immediate medical coverage and potential third-party lawsuits for pain and suffering — but only if the injured person meets the serious injury threshold under Insurance Law 5102(d). Understanding the interplay between first-party benefits and third-party litigation, police reports, comparative fault rules, and damages calculations is critical. These articles analyze the legal issues that arise in New York car accident cases across Long Island and NYC.
228 published articles in Car Accidents
Keep Reading
More Car Accidents Analysis
NY Proposes Prior Approval for Every Auto Rate Increase
DFS proposed a rule requiring prior approval for every private passenger auto rate increase in New York. What it means for your renewal after November 27, 2026.
Sep 15, 2026
Sunrise Highway Work-Zone Crash: Who Is Liable?
Two westbound Sunrise Highway lanes close overnight for a month. Who is liable in a work-zone crash: drivers, contractors, the State, and a 90-day clock.
Sep 9, 2026
What Happens at a Car Accident Trial in New York?
NY car accident trials: 9 stages, bifurcated liability/damages, §5102(d) threshold, Nassau vs. Bronx venue strategy. Long Island attorney. 516-750-0595.
Apr 5, 2026
Underinsured Motorist Coverage in New York Car Accidents: What You Need to Know
New York SUM coverage: bodily-injury limits, offsets, prompt notice, settlement consent and why triggering coverage does not guarantee payment.
Apr 4, 2026
Rollover Accident Settlement in New York: What Your Case Is Worth
Rollover accidents on Long Island can involve multiple defendants — other drivers, vehicle manufacturers, and tire companies.
Apr 4, 2026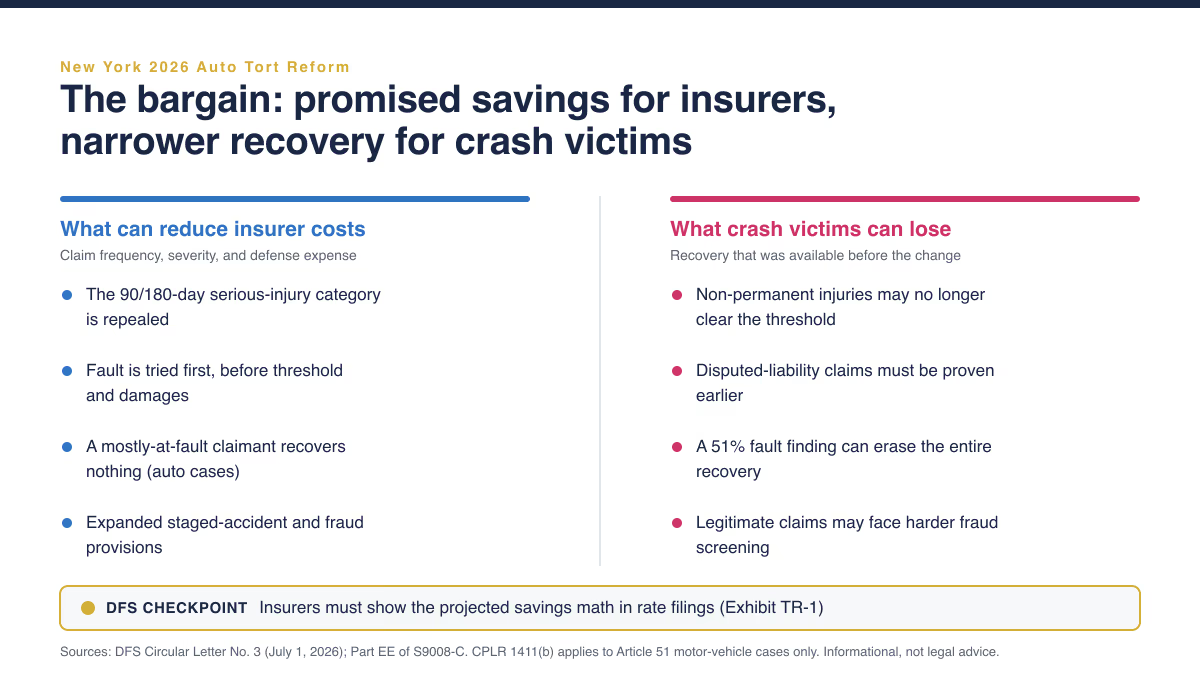
Will NY Auto Insurance Rates Go Down After Tort Reform? What Crash Victims Give Up
DFS Circular Letter No. 3 orders NY auto insurers to show their tort-reform savings math by Aug. 31, 2026. Here is what crash victims traded for it.
Aug 13, 2026Was this article helpful?
Disclaimer: This article is published by the Law Office of Jason Tenenbaum, P.C. for informational and educational purposes only. It does not constitute legal advice, and no attorney-client relationship is formed by reading this content. The legal principles discussed may not apply to your specific situation, and the law may have changed since this article was last updated.
New York law varies by jurisdiction — court decisions in one Appellate Division department may not be followed in another, and local court rules in Nassau County Supreme Court differ from those in Suffolk County Supreme Court, Kings County Civil Court, or Queens County Supreme Court. The Appellate Division, Second Department (which covers Long Island, Brooklyn, Queens, and Staten Island) and the Appellate Term (which hears appeals from lower courts) each have distinct procedural requirements and precedents that affect litigation strategy.
If you need legal help with a car accidents matter, contact our office at (516) 750-0595 for a free consultation. We serve clients throughout Long Island (Huntington, Babylon, Islip, Brookhaven, Smithtown, Riverhead, Southampton, East Hampton), Nassau County (Hempstead, Garden City, Mineola, Great Neck, Manhasset, Freeport, Long Beach, Rockville Centre, Valley Stream, Westbury, Hicksville, Massapequa), Suffolk County (Hauppauge, Deer Park, Bay Shore, Central Islip, Patchogue, Brentwood), Queens, Brooklyn, Manhattan, the Bronx, Staten Island, and Westchester County. Prior results do not guarantee a similar outcome.